MACY’S · Q2 FY2026 · INITIAL FINANCIAL REVIEW
Macy's: Growth is real. The EPS doubling needs a refund bridge.
Q2 FY2026 | Initial financial review · Results released September 10, 2026
Macy's grew comparable sales across all three nameplates. It also doubled reported EPS. Those statements describe different magnitudes of improvement: the quarter includes $0.23 of net tariff-refund benefit. Removing that benefit leaves adjusted EPS of approximately $0.40, up 14% from $0.35—not a doubling. [1]
Delta Sheet
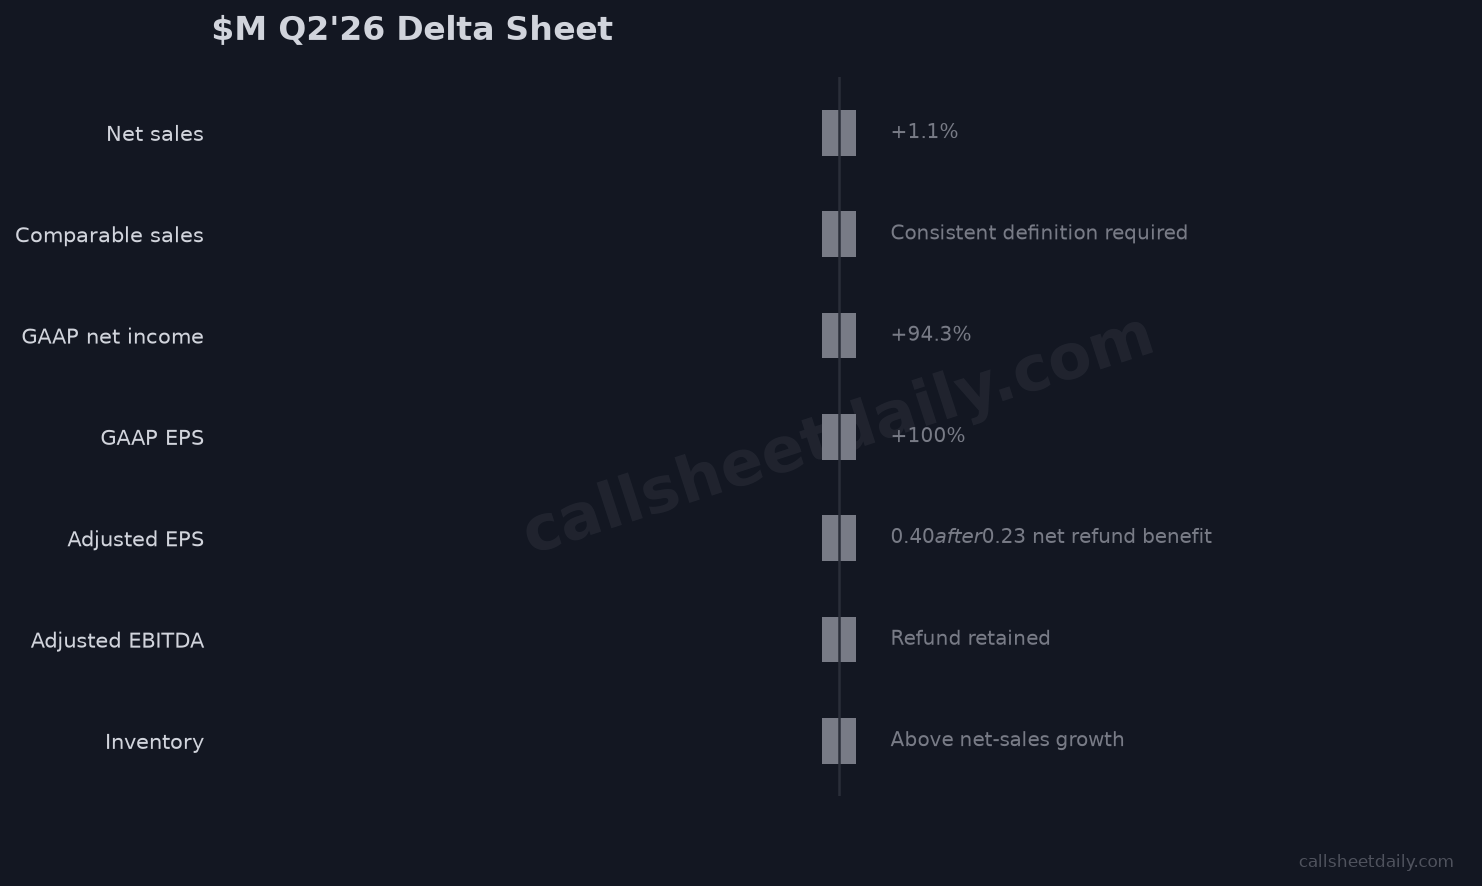
- Net sales: Prior / basis: Prior-year quarter; Current: $4.9B; Change or interpretation: +1.1%
- Comparable sales: Prior / basis: Owned + licensed + marketplace; Current: +2.7%; Change or interpretation: Consistent definition required
- GAAP net income: Prior / basis: $87M; Current: $169M; Change or interpretation: +94.3%
- GAAP EPS: Prior / basis: $0.31; Current: $0.62; Change or interpretation: +100%
- Adjusted EPS: Prior / basis: $0.35; Current: $0.63; Change or interpretation: $0.40 after $0.23 net refund benefit
- Adjusted EBITDA: Prior / basis: $373M; Current: $457M; Change or interpretation: Refund retained
- Inventory: Prior / basis: Prior-year quarter; Current: +2.5%; Change or interpretation: Above net-sales growth
Comparisons are year-over-year unless expressly labeled otherwise. [1]
Inside the full report
New Disclosures & Changes, Narrative Regressions, Binders vs Narrative, Promise Ledger, New Promises, Disclosure Quality Score, Financial Quality Indicators, AI Commentary, What to Verify, management questions and Bottom Line — including the refund-to-EPS bridge, reinvestment, comparable sales and management commitments.
Read the full M analysis →