KROGER · Q2 FY2026 · INITIAL FINANCIAL REVIEW
Kroger: The sales target falls. The EPS target survives.
Q2 FY2026 | Initial financial review · Results released September 11, 2026
Kroger cut its full-year identical-sales outlook while maintaining its profit and cash-flow targets. Q2 sales excluding fuel, disposals and selected fulfillment-center exits barely grew. Adjusted EPS nevertheless increased. The test is whether margin initiatives and buybacks can sustain per-share earnings without a recovery in customer demand. [1]
Delta Sheet
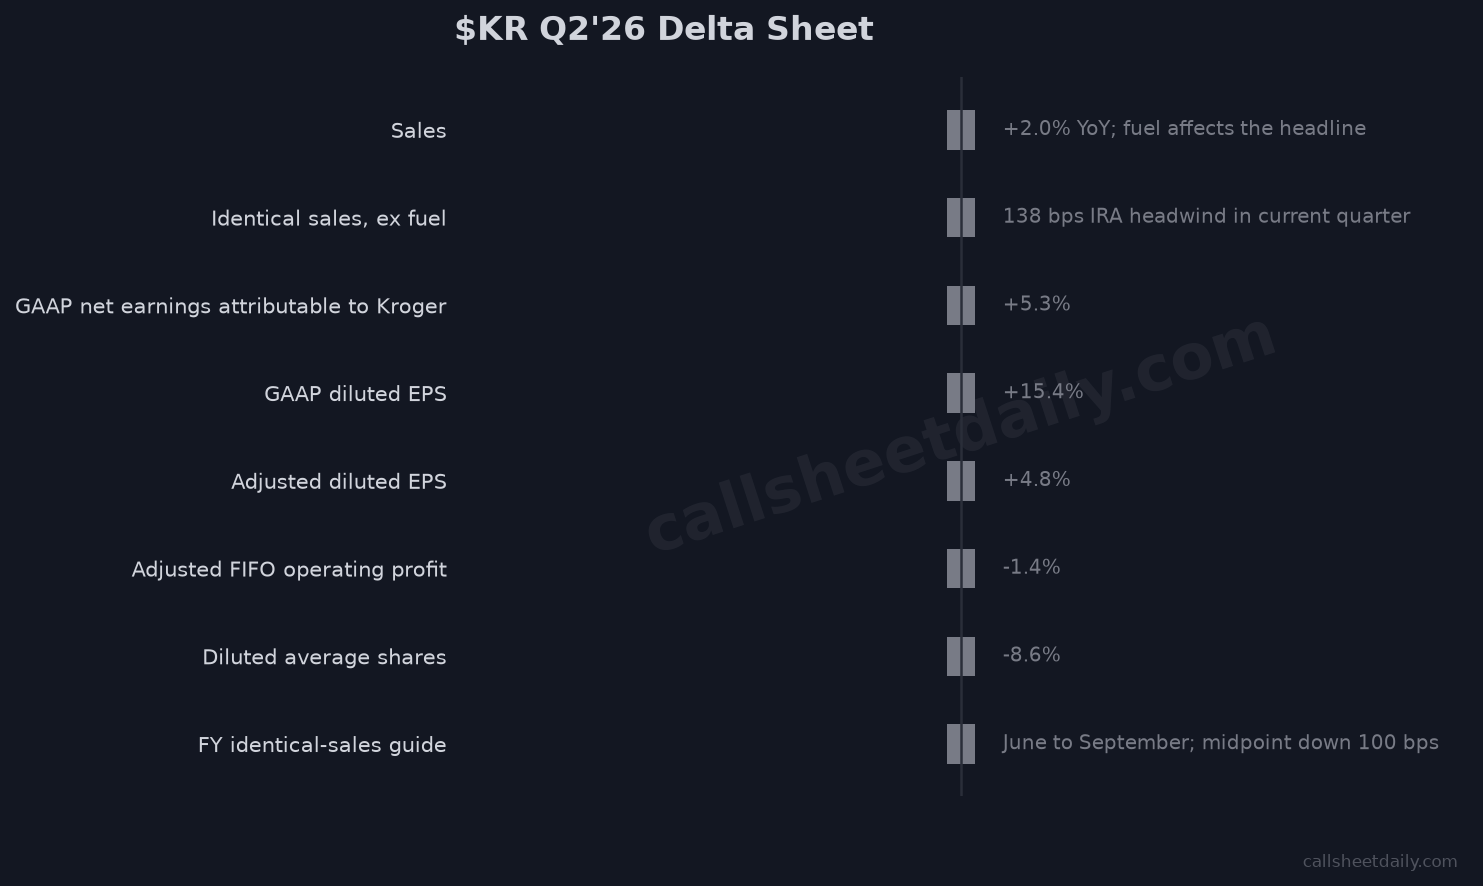
- Sales: Prior / basis: $33.940B; Current: $34.621B; Change or interpretation: +2.0% YoY; fuel affects the headline
- Identical sales, ex fuel: Prior / basis: +3.4%; Current: +0.2%; Change or interpretation: 138 bps IRA headwind in current quarter
- GAAP net earnings attributable to Kroger: Prior / basis: $609M; Current: $641M; Change or interpretation: +5.3%
- GAAP diluted EPS: Prior / basis: $0.91; Current: $1.05; Change or interpretation: +15.4%
- Adjusted diluted EPS: Prior / basis: $1.04; Current: $1.09; Change or interpretation: +4.8%
- Adjusted FIFO operating profit: Prior / basis: $1.091B; Current: $1.076B; Change or interpretation: -1.4%
- Diluted average shares: Prior / basis: 665M; Current: 608M; Change or interpretation: -8.6%
- FY identical-sales guide: Prior / basis: 1.0%–2.0%; Current: 0.2%–0.8%; Change or interpretation: June to September; midpoint down 100 bps
Comparisons are year-over-year unless expressly labeled otherwise. [1]
Inside the full report
New Disclosures & Changes, Narrative Regressions, Binders vs Narrative, Promise Ledger, New Promises, Disclosure Quality Score, Financial Quality Indicators, AI Commentary, What to Verify, management questions and Bottom Line — including the guidance reduction, share-count effect, refund attribution and management commitments.
Read the full KR analysis →