ADOBE (NASDAQ: ADBE) · Q3 FY2026 · EARNINGS ANALYSIS
Adobe: The AI audience is growing. Show the conversion to paid revenue.
Q3 FY2026 | Revenue and EPS beat guidance. Net income grew just 3%, and the acquired-revenue bridge became harder to follow.
Adobe beat the revenue and EPS targets it gave in June. Revenue rose 12.9% to $6.760 billion, and GAAP EPS rose 10.5% to $4.62. But net income rose only 3.1% to $1.827 billion. A smaller share count explains much of the difference between earnings growth and earnings-per-share growth. [1; 2]
The business is producing substantial cash. The question is whether the expanding freemium audience creates durable paid growth—and how much of the reported growth comes from Semrush. June supplied a clear acquisition contribution. When asked for an updated number in September, management emphasized integrated selling instead. That is the disclosure change to follow. [2; 3]
Delta Sheet
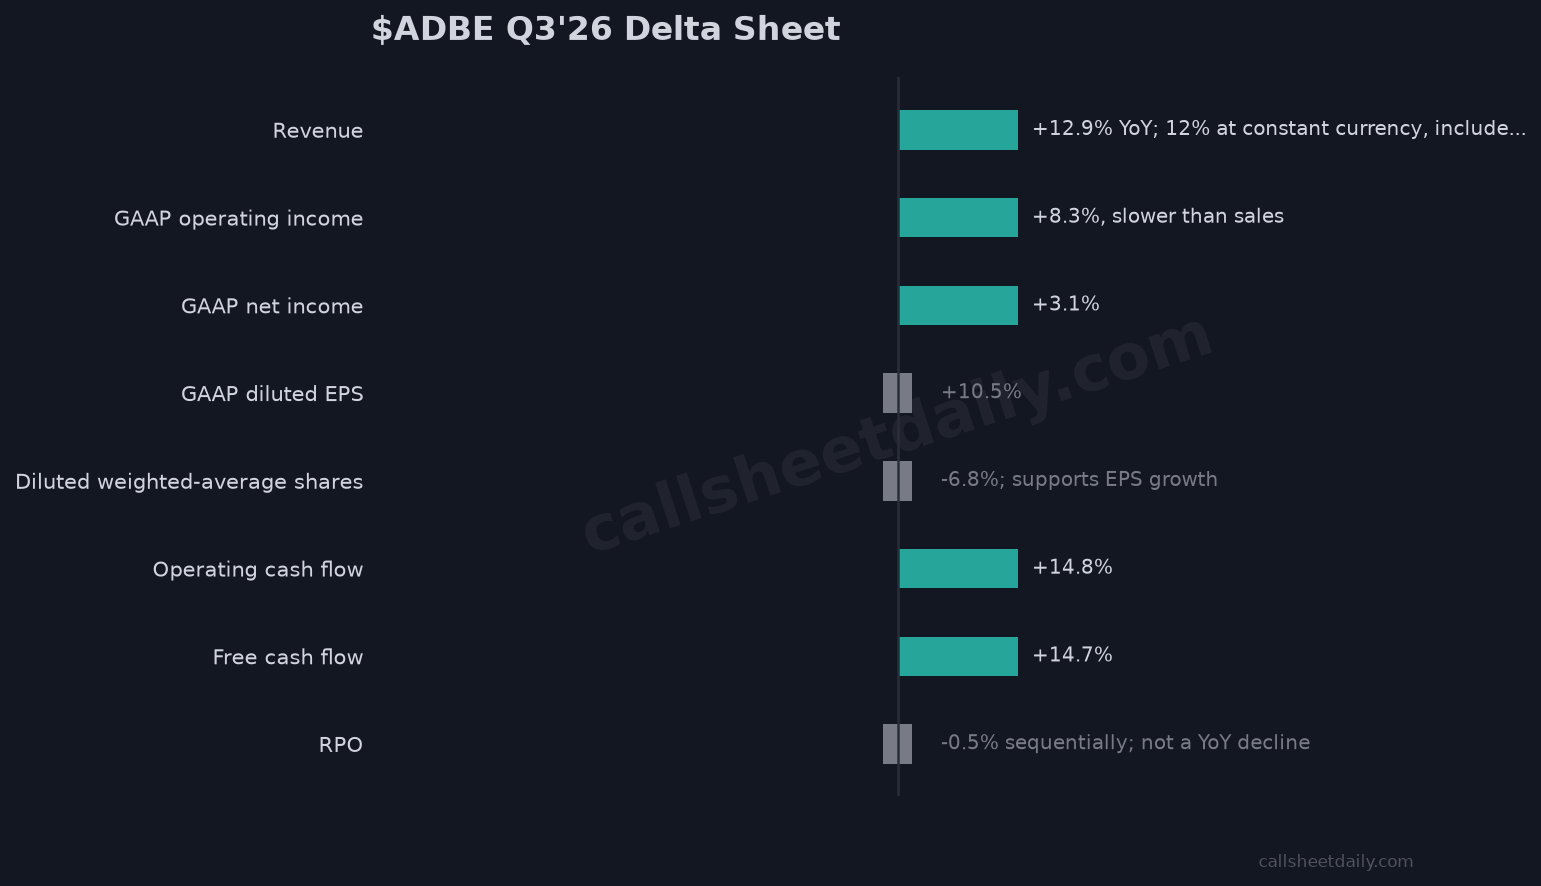
- Revenue: Prior comparison: $5.988B; Q3 FY2026: $6.760B; Meaning: +12.9% YoY; 12% at constant currency, includes acquisition
- GAAP operating income: Prior comparison: $2.173B; Q3 FY2026: $2.354B; Meaning: +8.3%, slower than sales
- GAAP net income: Prior comparison: $1.772B; Q3 FY2026: $1.827B; Meaning: +3.1%
- GAAP diluted EPS: Prior comparison: $4.18; Q3 FY2026: $4.62; Meaning: +10.5%
- Diluted weighted-average shares: Prior comparison: 424M; Q3 FY2026: 395M; Meaning: -6.8%; supports EPS growth
- Operating cash flow: Prior comparison: $2.198B; Q3 FY2026: $2.523B; Meaning: +14.8%
- Cash capex: Prior comparison: $72M; Q3 FY2026: $85M; Meaning: FCF calculated as CFO less capex
- Free cash flow: Prior comparison: $2.126B; Q3 FY2026: $2.438B; Meaning: +14.7%
- Ending ARR: Prior comparison: $27.10B, Q2; Q3 FY2026: $27.50B; Meaning: $400M sequential increase, using rounded endpoints
- RPO: Prior comparison: $22.27B, Q2; Q3 FY2026: $22.16B; Meaning: -0.5% sequentially; not a YoY decline
- FY2026 ARR growth guide: Prior comparison: 10.2%, June; Q3 FY2026: 10.2%; Meaning: Unchanged
- FY2026 adjusted EPS guide: Prior comparison: $24.35–$24.45; Q3 FY2026: $24.45–$24.50; Meaning: Raised
Unless labeled sequential or guidance, comparisons are with Q3 FY2025. Cash-flow figures are quarterly. ARR is an annualized operating metric, not quarterly revenue. [1; 2]
Inside the full report
New Disclosures & Changes, Narrative Regressions, Binders vs Narrative, Promise Ledger, New Promises, Disclosure Quality Score, Financial Quality Indicators, AI Commentary, What to Verify, management questions and Bottom Line — including the buyback-to-EPS bridge, acquired versus organic growth, AI monetization and management commitments.
Read the full ADBE analysis →